




摘要
- 人工智慧投資週期仍獲充分支持,需求正由早期基建建設擴展至主權人工智慧、企業應用及更廣泛的人工智慧普及。
- 投資機會也正延伸至人工智慧伺服器、電力、冷卻系統及資料中心基建,惠及晶片製造商以外的更廣泛企業。
- 亞洲科技供應鏈中,業務涉及半導體、先進封裝、記憶體、網絡及人工智慧伺服器基建的企業,包括電力及散熱管理公司,仍是主要受惠企業。
1. 你正關注哪些關鍵指標,以評估人工智慧相關投資週期是否仍可持續?
我們關注兩項關鍵指標:超大型雲端服務供應商的資本支出,以及全球資料中心的建設活動。部分預測顯示,全球最大型雲端服務供應商的雲端設備總支出預計將在2026年按年成長104%,2027年再按年成長38%(一個月內上調9個百分點),達至約1.61兆美元。這反映預測仍可能有進一步上調空間。
與此同時,近月我們追蹤的人工智慧資料中心項目數量已由約240個增至280個。預計未來兩至三年將有多個大型項目陸續展開,有望繼續為人工智慧硬體供應鏈帶來強勁且可預見的需求。
輝達最新業績及2028財政年度展望鞏固了我們對人工智慧基建週期的正面看法。該公司管理層預期,2028財政年度收入將成長約70%,高於市場預期,同時指出目前需求仍然高於供應。輝達也強調,主權人工智慧項目、NeoCloud服務供應商、人工智慧初創企業及企業客戶目前佔其業務約一半,成長年均複合成長率約100%。客戶來源多元化有助提升人工智慧資本支出的持續性,並降低其對少數大型雲端服務供應商的依賴。
這些指標均顯示,人工智慧投資週期已不再局限於早期基建建設階段,而超大型雲端服務供應商、主權人工智慧項目及企業採用人工智慧帶來的可預見需求,將在未來多年持續提供支持。
2. 哪些宏觀因素可能對人工智慧的投資依據構成挑戰?你又如何調整投資組合部署以應對這些風險?
主要風險包括資料中心建設限制及融資成本。項目許可、電力、電網接入、水資源供應及社區擔憂的因素均可能拖延項目進度,而利率則會影響融資及建設成本。
我們著重判斷這些挑戰會暫時延誤,抑或會動搖人工智慧的長期投資依據。若長期投資依據未受影響,我們將繼續持有相關投資,同時因應風險及估值變化調整持倉規模及投資組合結構。我們也分散投資於人工智慧價值鏈的不同環節,避免依賴單一項目、客戶或融資渠道。
3. 除了宏觀風險外,你如何評估亞洲科技投資人面對的政策及監管風險?
政策及監管風險不容忽視,大致可分為兩類。第一類是當地監管風險,包括與電力供應、環境影響、用水量及社區關注相關的限制或延誤。
第二類是地緣政治風險,尤其是中美之間的風險。例如,輝達及AMD高端產品出口至中國受到限制,以及美國可能限制進口部分中國製光學接收器。
我們會評估某個事件究竟是短期阻滯,抑或會對公司的競爭地位造成持久影響,並因應情況調整持倉、分散風險,或選擇性增持。
4. 科技股於7月顯著波動。投資人應否預期人工智慧相關投資的波動性將持續高檔?哪些因素預計將加劇波動?
波動性預計將持續高檔,原因是對人工智慧相關股票的預期及持倉比重偏高,而投資人也正仔細審視資本支出的持續性、融資結構、電力供應、供應限制,以及獲利兌現的速度。繼2026年第二季強勁上升後,即使基本面依然穩固,獲利回吐及估值壓縮也可能加劇短期市場波動。
我們認為,近期回調並不反映長期基本面轉差。人工智慧價值鏈各環節的需求繼續受惠於推理工作負載上升、運算基建的持續投資,以及半導體資本支出週期延續。我們繼續看好半導體、設備及記憶體企業,相關產業在多個領域仍然供不應求,尤其是記憶體產業。整體而言,我們將這輪拋售視為長期結構性成長趨勢下的正常修正,而人工智慧應用及數位轉型的核心推動因素依然穩健。
5. 目前的人工智慧投資依據中,你認為哪項假設最容易受到市場炒作或過度推斷的影響?
最容易受到挑戰的假設是人工智慧生態系統各環節都能維持相同的成長及估值擴張幅度。近期,投資人的憂慮集中於人工智慧基建支出的可持續性,以及部分領域可能出現產能過剩。雖然我們認為該產業的長期結構性前景不會明顯惡化,但投資人也不宜推斷短期成長將無限延續。
過去四年,各個科技子產業的表現往往會因市場對創新或產品規格變化的預期升溫而大幅領先,隨後在市場逐步消化相關預期後出現整固。因此,我們仍然看好整體人工智慧主題,同時會在估值、獲利可見度及個別公司的執行能力方面恪守投資紀律。
6. 你認為亞洲科技價值鏈中,哪些領域的投資價值仍被投資人低估?原因何在?
軟體、資訊科技服務及數位平台的表現一直落後於半導體及硬體,但隨着人工智慧應用趨於成熟,其有望受惠於生產力提升、產品功能增強及配備人工智慧功能的服務。我們認為,由於投資人的焦點由基建支出轉向人工智慧商業化,上述應用層企業可能成為下一個受惠領域。
機械人及自動駕駛技術也未獲充分重視。這些領域目前在獲利貢獻及投資人認可上仍處於早期階段,但隨着商業應用前景及獲利能力日趨明朗,其估值有望得到重估。憑藉製造、零件及供應鏈整合優勢,亞洲在這些領域尤其佔優。
7. 隨着人工智慧基建投資日益依賴債務、股權、私人信用及表外融資架構,融資環境會否對人工智慧的投資依據構成更大風險?
融資環境及資產負債表紀律變得愈來愈重要。雖然人工智慧投資步伐加快或會導致部分雲端服務供應商的短期自由現金流受壓,但人工智慧依然是其成長最快、策略重要性最高的業務之一,並可帶動更廣泛的雲端服務需求。
大型雲端服務供應商仍具備擴展人工智慧基建的財務能力,而我們未見目前的融資環境有跡象顯示人工智慧資本支出週期即將出現轉折。相反,我們著重區分資本充裕、需求前景明朗的營運商,以及依賴高槓桿或透明度較低的融資架構的項目。
8. 投資人可從亞洲近期業績中得到什麼借鑑與啟示?
亞洲2026年第二季業績表現強勁,市場對2026年及2027年的獲利預期也持續上調。根據彭博最新市場共識預測,亞洲科技企業的獲利成長預計將顯著跑贏全球同業,2026年每股獲利成長預測為212%,2027年為42%。因此,我們認為近期市場回調為投資人提供逐步建立相關配置的機會。
圖1︰獲利預期
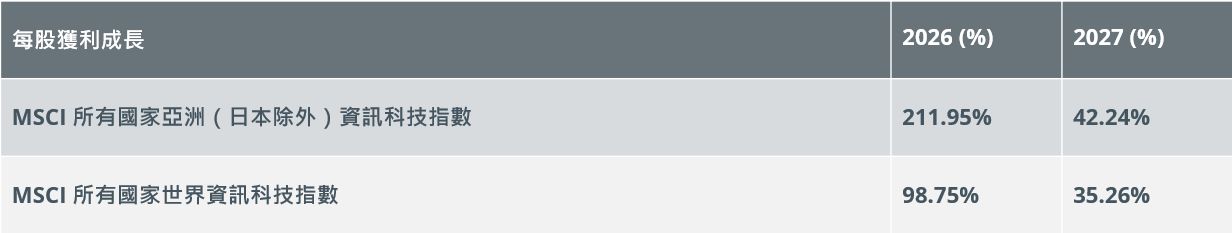
資料來源︰彭博,2026年8月
更多文章


Singapore and Australia (for wholesale clients only) by Eastspring Investments (Singapore) Limited (UEN: 199407631H), which is incorporated in Singapore, is exempt from the requirement to hold an Australian financial services licence and is licensed and regulated by the Monetary Authority of Singapore under Singapore laws which differ from Australian laws.
Hong Kong by Eastspring Investments (Hong Kong) Limited and has not been reviewed by the Securities and Futures Commission of Hong Kong.
Indonesia by PT Eastspring Investments Indonesia, an investment manager that is licensed, registered and supervised by the Indonesia Financial Services Authority (OJK).
Malaysia by Eastspring Investments Berhad (531241-U).
United States of America (for institutional clients only) by Eastspring Investments (Singapore) Limited (UEN: 199407631H), which is incorporated in Singapore and is registered with the U.S Securities and Exchange Commission as a registered investment adviser.
European Economic Area (for professional clients only) and Switzerland (for qualified investors only) by Eastspring Investments (Luxembourg) S.A., 26, Boulevard Royal, 2449 Luxembourg, Grand-Duchy of Luxembourg, registered with the Registre de Commerce et des Sociétés (Luxembourg), Register No B 173737.
United Kingdom (for professional clients only) by Eastspring Investments (Luxembourg) S.A. - UK Branch, 10 Lower Thames Street, London EC3R 6AF.
Chile (for institutional clients only) by Eastspring Investments (Singapore) Limited (UEN: 199407631H), which is incorporated in Singapore and is licensed and regulated by the Monetary Authority of Singapore under Singapore laws which differ from Chilean laws.
The afore-mentioned entities are hereinafter collectively referred to as Eastspring Investments.
The views and opinions contained herein are those of the author on this page, and may not necessarily represent views expressed or reflected in other Eastspring Investments’ communications. This document is solely for information purposes and does not have any regard to the specific investment objective, financial situation and/or particular needs of any specific persons who may receive this document. This document is not intended as an offer, a solicitation of offer or a recommendation, to deal in shares of securities or any financial instruments. It may not be published, circulated, reproduced or distributed without the prior written consent of Eastspring Investments. Reliance upon information in this posting is at the sole discretion of the reader. Please consult your own professional adviser before investing.
Investment involves risk. Past performance and the predictions, projections, or forecasts on the economy, securities markets or the economic trends of the markets are not necessarily indicative of the future or likely performance of Eastspring Investments or any of the funds managed by Eastspring Investments.
Information herein is believed to be reliable at time of publication. Data from third party sources may have been used in the preparation of this material and Eastspring Investments has not independently verified, validated or audited such data. Where lawfully permitted, Eastspring Investments does not warrant its completeness or accuracy and is not responsible for error of facts or opinion nor shall be liable for damages arising out of any person’s reliance upon this information. Any opinion or estimate contained in this document may subject to change without notice.
Eastspring Investments (excluding JV companies) companies are ultimately wholly-owned/indirect subsidiaries/associate of Prudential plc of the United Kingdom. Eastspring Investments companies (including JV’s) and Prudential plc are not affiliated in any manner with Prudential Financial, Inc., a company whose principal place of business is in the United States of America or with the Prudential Assurance Company, a subsidiary of M&G plc (a company incorporated in the United Kingdom).