




摘要
- 隨著結構性成長主題帶動企業獲利及自由現金流成長,加上企業治理改革令企業更重視股東報酬,亞洲市場的股息潛力持續提升。
- 在成長股主導的股市升勢中,傳統高股息策略或面臨挑戰,因為主要篩選當前殖利率最高股票的策略,往往偏好成熟企業及價值型產業。
- 採取前瞻性亞洲股票收益策略,有望把握穩定收益、股息成長及配息回升這三種互補性報酬來源,助投資人實現具吸引力的總報酬。
債券殖利率上升,加上亞洲股市強勁上漲,可能促使投資人重新評估股息投資策略。然而,我們的分析顯示,透過採取前瞻性亞洲股票收益策略,有望把握穩定收益、股息成長及配息回升這三種互補性報酬來源,助投資人實現具吸引力的總報酬。
股息的不同階段
一間中國貨車引擎製造商、一間台灣半導體服務公司,以及一間新加坡電訊集團,究竟有何共通點?乍看之下,三者的共通點似乎不多。然而,三間公司分別展示了股息如何循不同途徑為投資人帶來報酬。
就中國貨車引擎製造商而言,我們觀察到股息隨著基本面改善而回升的機會。此前,產業氣氛低迷,掩蓋了中國以舊換新補貼、汰換需求,以及排放標準升級帶來的潛在好處。隨著該公司的獲利及現金流改善,其配息能力也有所增強。
台灣半導體服務公司方面,我們預計其強勁的結構性獲利成長將支撐股息成長。該公司從事先進半導體封裝及測試業務,因此能夠受惠於人工智慧(AI)基礎建設發展帶來的投資機會。此外,該公司公佈的配息比率達70%,使獲利成長能更直接地轉化為股東配息。
至於新加坡電訊集團方面,我們的初步判斷是其成熟業務為穩定配息提供支持。然而,該公司的股息潛力不止於此。透過資產循環及提升股東報酬的舉措,該公司在原有的穩健收益基礎上,增加了新的股息成長動力。
這三間公司處於不同的股息階段,說明了收益型投資策略應著眼未來。最具吸引力的投資機會未必來自當前殖利率最高的股票。因此,我們不會僅著眼於當前殖利率,而會評估一間公司的整個股息週期。
在投資人正思考以下三個重要問題之際,這一點尤其重要:
1. 在債券殖利率較高的環境下,為何仍持有配息股?
2. 亞洲股市強勁上升,採取收益型投資策略會否犧牲成長?
3. 股息投資策略能否擺脫防守或價值投資風格的限制?
要回答這三個問題,都始於同一個關鍵:不只看眼前的股息殖利率。
殖利率僅為收益投資的一環
債券殖利率較高,導致收益型資產吸引投資資金的競爭加劇。然而債券與配息股在投資組合中發揮不同作用,並承擔不同風險。因此,資產配置決策時應建基於投資人對總報酬、收益成長及風險水平的要求,而非單純比較股票的當前股息率與債券殖利率。
- 當前股息
- 未來股息成長
- 資本增值
從歷史經驗來看,股息一直是亞洲股票長期報酬的重要來源。在過去20年約佔總報酬的40%,突顯其在長線財富增值方面的重要性。與此同時,亞洲企業的股息潛力持續提升。
- 受惠於人工智慧相關投資及基礎建設支出等結構性成長主題,亞洲各地企業的獲利預期持續改善。
- 亞洲企業(主要為北亞企業)的自由現金流正以前所未有的速度成長,預計將支持企業增加配息及股份回購。
- 中國及韓國等市場的企業治理改革也促使企業更重視股東報酬,為收益型投資帶來更多機會。
圖1. 亞洲企業自由現金流加速成長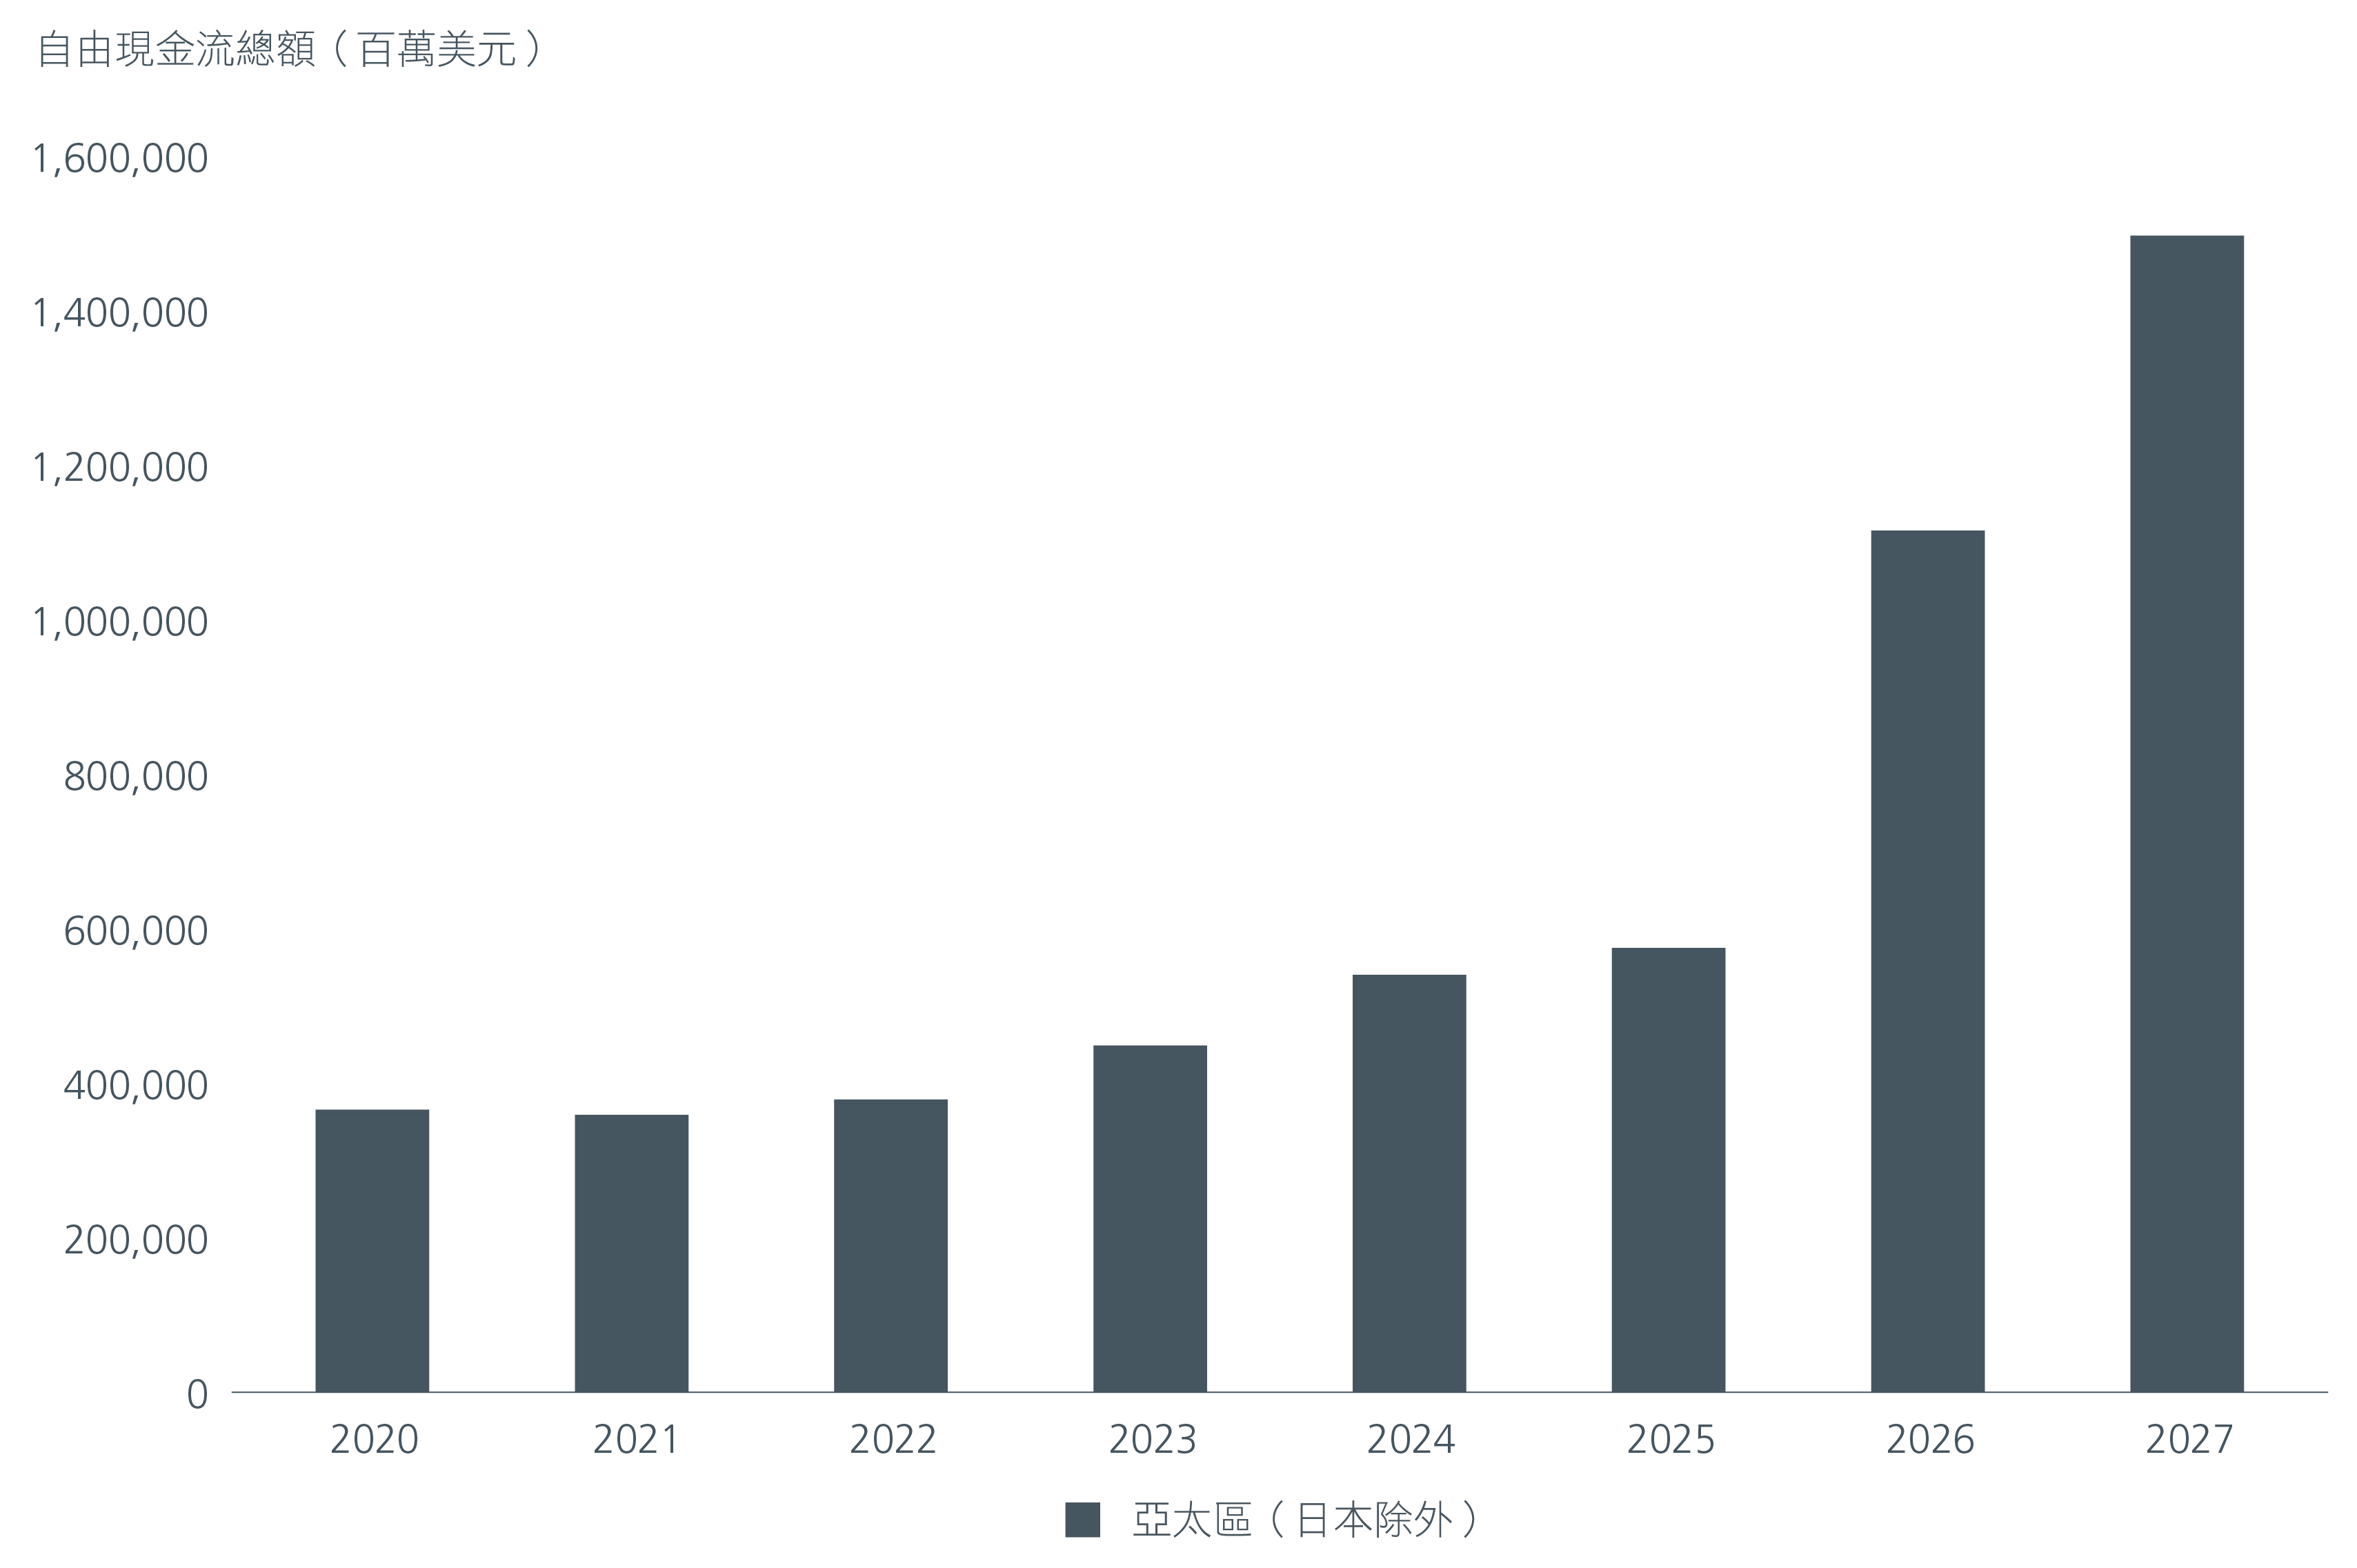
資料來源:瀚亞投資。里昂證券亞太區(日本除外)投資範圍。2026年10月6日
兼顧收益與成長
在成長股主導的股市升勢中,傳統高股息策略或面臨挑戰,因為主要篩選當前殖利率最高股票的策略,往往偏好成熟企業及價值型產業,並忽略再投資於新興成長機會的公司。
然而,透過在投資組合中結合配息穩定、股息成長及殖利率回升的股票,我們使投資人能同時實現收益與成長。股息成長或殖利率回升的企業,往往先受惠於獲利成長及對股東報酬的日益關注,然後再成為傳統高殖利率股票。
這種不只著眼於當前股息殖利率的投資方式,我們得以維持收益紀律及避免過度集中風險,同時參與台灣及韓國科技及人工智慧相關投資機會。我們的目標既不是為追求最高殖利率而放棄成長,也不是為追逐成長而忽略收益,而是力求兼顧可持續收益、股息成長及資本增值,實現均衡的總報酬表現。
透過不受風格限制的主動策略提升韌性
新興市場債券已不再是1990年代集中於受壓債務的小眾市場,其市場廣度、信用品質及可投資性均超出不少投資人的既有認知。截至2025年12月,全球新興市場可交易債務總額達52兆美元,約佔全球未償還債券總額的31%,規模略低於美國,但高於歐盟。
更多文章


Singapore and Australia (for wholesale clients only) by Eastspring Investments (Singapore) Limited (UEN: 199407631H), which is incorporated in Singapore, is exempt from the requirement to hold an Australian financial services licence and is licensed and regulated by the Monetary Authority of Singapore under Singapore laws which differ from Australian laws.
Hong Kong by Eastspring Investments (Hong Kong) Limited and has not been reviewed by the Securities and Futures Commission of Hong Kong.
Indonesia by PT Eastspring Investments Indonesia, an investment manager that is licensed, registered and supervised by the Indonesia Financial Services Authority (OJK).
Malaysia by Eastspring Investments Berhad (531241-U).
United States of America (for institutional clients only) by Eastspring Investments (Singapore) Limited (UEN: 199407631H), which is incorporated in Singapore and is registered with the U.S Securities and Exchange Commission as a registered investment adviser.
European Economic Area (for professional clients only) and Switzerland (for qualified investors only) by Eastspring Investments (Luxembourg) S.A., 26, Boulevard Royal, 2449 Luxembourg, Grand-Duchy of Luxembourg, registered with the Registre de Commerce et des Sociétés (Luxembourg), Register No B 173737.
United Kingdom (for professional clients only) by Eastspring Investments (Luxembourg) S.A. - UK Branch, 10 Lower Thames Street, London EC3R 6AF.
Chile (for institutional clients only) by Eastspring Investments (Singapore) Limited (UEN: 199407631H), which is incorporated in Singapore and is licensed and regulated by the Monetary Authority of Singapore under Singapore laws which differ from Chilean laws.
The afore-mentioned entities are hereinafter collectively referred to as Eastspring Investments.
The views and opinions contained herein are those of the author on this page, and may not necessarily represent views expressed or reflected in other Eastspring Investments’ communications. This document is solely for information purposes and does not have any regard to the specific investment objective, financial situation and/or particular needs of any specific persons who may receive this document. This document is not intended as an offer, a solicitation of offer or a recommendation, to deal in shares of securities or any financial instruments. It may not be published, circulated, reproduced or distributed without the prior written consent of Eastspring Investments. Reliance upon information in this posting is at the sole discretion of the reader. Please consult your own professional adviser before investing.
Investment involves risk. Past performance and the predictions, projections, or forecasts on the economy, securities markets or the economic trends of the markets are not necessarily indicative of the future or likely performance of Eastspring Investments or any of the funds managed by Eastspring Investments.
Information herein is believed to be reliable at time of publication. Data from third party sources may have been used in the preparation of this material and Eastspring Investments has not independently verified, validated or audited such data. Where lawfully permitted, Eastspring Investments does not warrant its completeness or accuracy and is not responsible for error of facts or opinion nor shall be liable for damages arising out of any person’s reliance upon this information. Any opinion or estimate contained in this document may subject to change without notice.
Eastspring Investments (excluding JV companies) companies are ultimately wholly-owned/indirect subsidiaries/associate of Prudential plc of the United Kingdom. Eastspring Investments companies (including JV’s) and Prudential plc are not affiliated in any manner with Prudential Financial, Inc., a company whose principal place of business is in the United States of America or with the Prudential Assurance Company, a subsidiary of M&G plc (a company incorporated in the United Kingdom).